What Subscription Operators Miss About Built-In Retries (Oct 2026)
If your billing platform retries run on a fixed 14-to-21-day countdown from the failure date, they have no idea when your subscriber's paycheck actually cleared. They don't read Merchant Advice Codes that tell them whether to wait one hour or stop completely. And they can't distinguish a temporary bank-side block from a card flagged for fraud. This post walks through exactly where that default retry logic breaks down and what a smarter approach actually looks like.
TLDR:
- Built-in retry logic from Stripe, Chargebee, and Recurly runs fixed date-based schedules that ignore decline codes, MAC signals, and subscriber pay cycles.
- Failed payments drive roughly 50% of involuntary churn; for a $10M ARR (annual recurring revenue) business, that translates to $1 to $2M in recoverable revenue lost annually.
- Retrying hard declines damages your merchant ID (MID, your billing identity with card networks) reputation and triggers card network penalties: Mastercard charges $0.10 per retry after a "do not retry" instruction.
- Retry timing outweighs retry count; three well-timed attempts on a soft decline outperform seven attempts fired on the wrong days.
- Slicker's retry engine weighs over 40 variables per transaction and uses AABB testing (a controlled crossover test) to measure dollars recovered against your billing tool's native retries before any financial commitment.
Why Billing Platform Retries Fall Short on Failed Payments
Every major billing system ships with retry logic out of the box. Stripe Billing has Smart Retries. Chargebee has Smart Dunning. Recurly has its own revenue optimization layer. All of them do something when a payment fails, and that's exactly the problem: operators assume "something" is "enough."
Built-in retries typically follow a fixed schedule. A payment fails, the system waits a few days, tries again, waits again, and repeats until the invoice closes or the subscription cancels. The timing is generic, the logic doesn't read decline codes deeply, and it doesn't adjust based on what the issuer actually told your processor.
That default configuration recovers some revenue, but leaves a measurable share on the table by treating every failed payment the same way.
The Real Scale of the Involuntary Churn (Involuntary Churn) Problem
Involuntary churn accounts for 20 to 40% of all subscription cancellations, meaning a large share of lost subscribers never chose to leave. Failed payments drove roughly 50% of that involuntary loss, according to PYMNTS data, and about 15% of recurring transactions decline each billing cycle.
For a $10M ARR (annual recurring revenue) business running 5% monthly churn, 1 to 2 percentage points of that is payment-driven: $1 to $2M annually in revenue already earned, from customers already paying, lost because a retry fired at the wrong time or not at all.
Retry logic is a revenue decision, not a billing configuration detail.
Soft Declines vs. Hard Declines: Why the Distinction Defines Everything
The distinction between soft vs hard declines is foundational: soft declines are temporary, covering insufficient funds, network timeouts, and brief processor errors where the card is valid and a well-timed retry will often succeed, while hard declines are permanent. Stolen cards, closed accounts, fraud flags: no retry will change the outcome.
Most billing tools with built-in retry settings treat these two categories similarly, firing retries on a fixed schedule regardless of what the issuer actually communicated. That produces two failure modes at once: missed recoveries on soft declines retried at the wrong time, and wasted attempts on hard declines that will never authorize.
The downstream cost of the second failure mode is worse than it looks. Retrying a hard decline can damage your merchant ID (MID) reputation, lowering authorization rates on future charges across your entire subscriber base. Card networks also penalize excessive reattempts. Mastercard charges $0.10 per retry when a decline carries a "do not retry" instruction, and PayPal's overview of retry penalties, with per-transaction fees for violations.
Getting the classification right is the prerequisite for everything else in a retry strategy.
What Default Retry Schedules Actually Look Like
Most billing tools space retry attempts across a fixed 14-to-21-day window. Stripe describes its logic as "smart," but in practice it applies a default calendar uniformly across your subscriber base. Chargebee's Smart Dunning follows the same pattern: configurable intervals with limited decline-code routing that won't distinguish a temporary bank-side block from a velocity flag triggered by fraud. Recurly adds some decline-code awareness, but retry windows remain largely fixed.
The shared structural constraint is that these systems operate within their own data. They read the gateway response code, apply a rule, and schedule the next attempt. None of them read Merchant Advice Codes at the depth required to know whether "do not honor" means retry in six days or stop entirely.
The practical result looks roughly like this:
Attempt | Typical Timing |
|---|---|
1st retry | 3-5 days after failure |
2nd retry | 5-7 days after first retry |
3rd retry | 7-10 days after second retry |
Final closure | Day 14-21 |
Timing is date-based, not hour-based. Your subscriber's paycheck cleared at 12:01am, but the retry fires at 2pm. That gap is recoverable revenue left on the table by a schedule that has no awareness of when funds are actually available.
The Card Network Retry Rules Your Billing Platform May Not Enforce
Visa and Mastercard payment retry rules are explicit: Visa allows 20 retries in 30 days on soft declines and prohibits retries on hard declines entirely, with per-transaction fees for violations, while Mastercard caps soft decline retries at 10 attempts within 24 hours.
Mastercard updated its Excessive Authorization Attempts policy in January 2026, applying stricter oversight and increased penalties to merchants whose billing systems repeatedly retry declined transactions, with subscription and SaaS businesses called out by name. Fee exposure scales directly with retry volume, and a billing tool running unchecked retries on a large subscriber base will breach these limits without any visible alert. Verify current program rules in Mastercard's official rules, as requirements may have changed since January 2026.
The gap: most billing tools enforce their own retry caps without verifying compliance against card network rules per BIN. Your tool's "maximum attempts" setting and Mastercard's program limits are two separate things that do not automatically align, and that misalignment has a direct cost.
Why Retry Timing Matters More Than Retry Count
A billing tool that fires three retries in the right windows will outperform one firing seven retries on the wrong days. Retry count is a ceiling; timing is what determines how close you get to it.
The core problem with fixed schedules is that they ignore when funds are actually available. Consumer debit cards in the US are most likely to authorize at 12:01am, when payroll deposits clear. A retry firing at 2pm that same day catches an account that may already be drawn down.
Payroll cadences vary by geography and compound this problem:
- US subscribers are typically paid biweekly, with funds arriving around the 1st and 15th of the month.
- UK and Western European subscribers are often paid monthly, near the last working day of the month.
- Australian payroll cycles can be weekly or fortnightly.
A single retry schedule applied globally misaligns with most of these windows for most subscribers most of the time. A subscriber with insufficient funds on billing day has a meaningfully higher probability of authorizing two to three days after their next paycheck clears. Fixed schedules fire on a countdown from the original failure date, which may have no relationship to the subscriber's actual pay cycle. That gap is where revenue leaks.
Merchant Advice Codes (MACs): The Signal Most Billing Platforms Ignore
When a Mastercard transaction declines, the response often carries more than a refusal. It carries an instruction. Merchant Advice Codes (MACs) tell you exactly what to do next: wait 24 hours, wait 10 days, update account details, or stop retrying entirely.
Most billing tools don't read them.
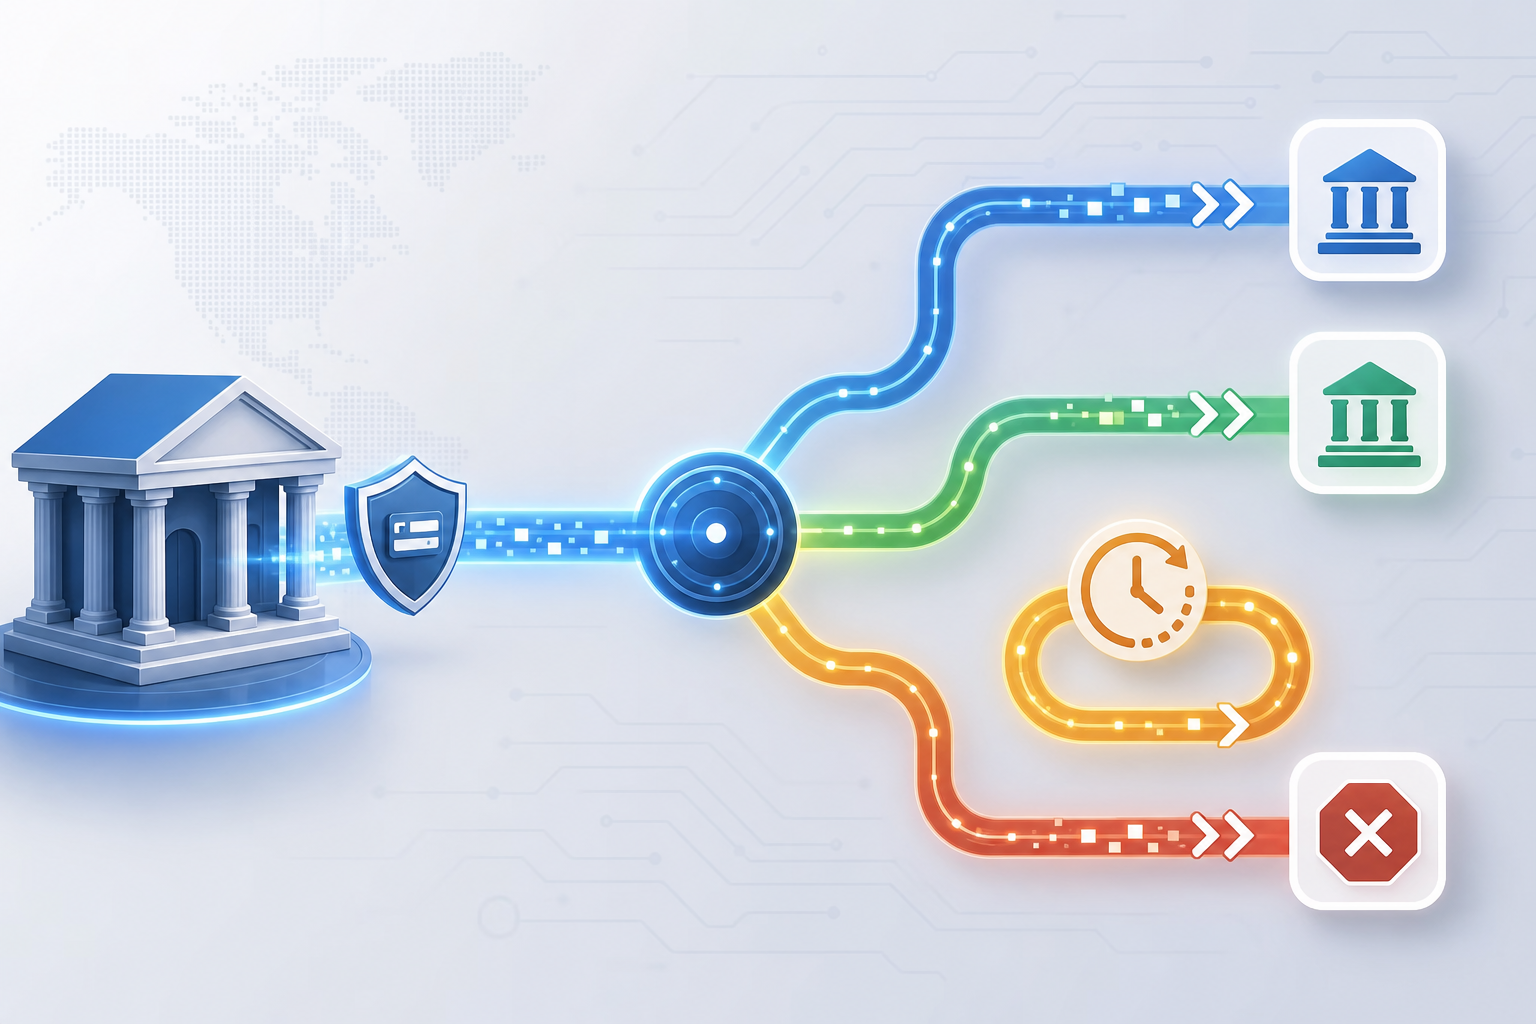
MAC 03 (Do Not Try Again) carries a direct fee consequence: retrying after receiving it costs $0.10 per attempt under Mastercard's Excessive Attempts program. MAC 21 (Stop Recurring Payment) signals a cardholder-initiated cancellation of recurring billing, so retrying it risks chargebacks, though the $0.10-per-attempt fee is specific to MAC 03.
The timing codes are where fixed schedules fail structurally:
MAC Code | Instruction |
|---|---|
24 | Retry after 1 hour |
25 | Retry after 24 hours |
26 | Retry after 2 days |
27 | Retry after 4 days |
28 | Retry after 6 days |
29 | Retry after 8 days |
30 | Retry after 10 days |
A billing tool running a fixed 3-5 day retry interval cannot honor a MAC 24 instruction to retry in one hour, nor hold for 10 days when MAC 30 says waiting is the right call. That mismatch means either missing the optimal recovery window or firing a retry too early and accumulating unnecessary decline history with the issuer. Poor retry behavior against issuer instructions degrades your authorization rate on future attempts, so the cost extends well beyond any single penalty fee.
The Hidden Risk of Retrying Hard Declines
Retrying a hard decline is a different category of mistake from retrying at the wrong time. A mistimed retry on a soft decline costs you one recovery opportunity. A retry on a stolen card, a closed account, or a fraud-flagged instrument costs you more with each attempt.
The merchant ID (MID) absorbs the accumulated damage. Card networks and issuers track retry behavior at the MID level. When your billing system repeatedly attempts hard declines, your authorization rate on legitimate customer-initiated payments drops across the board. Subscribers who would have authorized cleanly start failing, and the cause is invisible in a standard billing dashboard that doesn't link retry behavior to authorization rate degradation.
The hard decline retry penalties compound this. Mastercard charges $0.10 per retry on any attempt made after receiving MAC 03 (Do Not Try Again). Visa's Excessive Reattempts Program applies fees for retrying hard declines. At volume, neither is a rounding error.
Most billing tools don't surface this exposure because their dashboards show retry counts and recovery rates, not decline-code-level retry breakdowns. You can see that 200 retries ran last week without seeing how many fired against codes that should have been permanent stops.
When Retries Alone Are Not Enough: The Case for Dunning as a Fallback
Automated retries work precisely because they're invisible. The subscriber never knows a payment failed; the system recovers it quietly and the subscription continues.
But some failure types can't be resolved without the subscriber. A stolen card won't authorize regardless of timing. An expired card needs replacement details. In these cases, retrying is wasted effort, and the only path to recovery is direct outreach asking the subscriber to act.
Most billing tools blur this boundary. Stripe Smart Retries ties email sends to retry attempts, so a temporary bank-side block can trigger a "please update your payment method" notification before any retry has even run. Understanding smart dunning versus rules-based recovery clarifies why that sequencing matters. That burns subscriber trust for a failure that would have resolved on its own.
The correct order is: retry silently first, exhaust the recoverable window, then escalate to dunning only when the failure code confirms customer action is the only remaining path. A failure reason dunning cadence routes each decline accordingly. Most out-of-the-box configurations don't make that structural decision for you.
How to Measure Whether Your Retry Strategy Is Actually Working
Most billing dashboards show you a recovery rate. Few show you whether that recovery rate is actually good.
The right starting point is the gap between your initial failure rate and your final failure rate after the full retry window closes. Initial failure rate tells you how often payments decline on the first attempt. Final failure rate tells you how many stay unrecovered after every retry runs. The delta between them is your retry strategy's real output, and most billing dashboards report only the first number.
A few metrics worth tracking directly:
- Initial vs. final failure rate by decline code, not in aggregate. A well-tuned engine should close more than half the gap between your initial and final failure rate; if final failure rate is within 1 to 2 percentage points of your initial rate, retries are contributing almost nothing.
- Recovery rate on soft declines, separated from hard declines. A healthy soft-decline recovery rate is typically above 60%; below 40% suggests the timing or code routing is off.
- Time-to-recovery: how many days elapsed between first failure and successful charge. Under 7 days signals well-timed attempts aligned to payday windows; consistently above 14 days points to a fixed schedule that is not reading pay cycles.
- Retry attempts per recovered invoice versus attempts per unrecovered invoice. If both numbers are similar (e.g., 3.8 vs. 4.1), timing and code routing are not the driver; a well-structured engine recovers most soft declines in 2 to 3 attempts, not 5 to 7.
The third metric reveals timing quality. If recovered invoices average four attempts and unrecovered ones also average four, timing and code routing likely are not the driver. A well-structured retry engine recovers most soft declines in 2 to 3 attempts; if your average climbs above 5, you are likely firing retries on the wrong days or against codes that will not authorize regardless of timing.
The harder measurement question is whether your current retry logic is outperforming the alternative. The only defensible way to answer that is a controlled test: AABB testing in payment recovery splits failed payments into a control group running your billing tool's native retries and a treatment group running a different strategy, measures dollars recovered per group, and calculates statistical significance before drawing conclusions. Recovery rate comparisons without a control group and a p-value are vendor benchmarks, not evidence.
How Slicker Closes the Gaps Built-In Retries Leave Behind
Slicker's retry engine was built around the specific failure modes this post has described. Instead of applying a fixed schedule, an ensemble of AI models weighs over 40 variables per transaction: card type, issuer behavior, regional payday calendars, Merchant Advice Code signals, and historical retry outcomes at the BIN level. The result is hour-level timing precision, not a date-based countdown from the failure event.
The measurement gap gets closed through AABB testing, a crossover design borrowed from clinical trials. Failed payments split 50/50 between your billing tool's native retries and Slicker's engine, dollars recovered are measured per group, and statistical significance is calculated before any financial commitment. If Slicker doesn't outperform with a meaningful p-value, you don't pay.
The gap between built-in and add-on retry tools is why setup on supported billing tools, including Stripe Billing, Chargebee, Recurly, Zuora, and Recharge, takes under 5 minutes with zero engineering lift required.
Final Thoughts on Why Billing Platform Retry Logic Falls Short
Out-of-the-box retry settings treat a stolen card and a temporarily short account the same way, and that's where recoverable revenue quietly disappears. Timing, decline code routing, and MAC signal awareness are what separate a retry strategy that actually works from one that just runs. Your subscriber base deserves better than a fixed countdown. Get in touch with the Slicker team if you want to run a real test against your current setup.
FAQs
How do Slicker's retries work alongside Stripe Smart Retries without conflicting?
Slicker runs as an overlay on Stripe Billing, splitting failed payments between Stripe's native retry logic (control group) and Slicker's AI retry engine (treatment group) during evaluation. For this to work correctly, you must extend Stripe's default subscription cancellation grace period to match Slicker's multi-week retry windows; if Stripe closes a subscription before Slicker can execute its attempts, those recovery opportunities are lost. In full orchestration deployments where Slicker manages complex subscription handling, Stripe Smart Retries must be disabled entirely to avoid conflicts.
How do I avoid Visa and Mastercard retry fees when retrying failed subscription payments?
Stop retrying before network limits and decline-code instructions say to. Visa caps retries at 15 attempts per 30 days per card and amount on soft declines, prohibits retries on hard declines entirely, and charges per-transaction fees for violations. Mastercard allows 10 soft decline retries within 24 hours and charges $0.10 per attempt when you retry after receiving MAC 03 (Do Not Try Again). Separately, retrying after MAC 21 (Stop Recurring Payment) risks chargebacks, since the code signals a cardholder-initiated cancellation of recurring billing. The gap most billing platforms miss is that their own "maximum attempts" setting and card network program limits are two separate thresholds that do not automatically align, so breaching network rules incurs fees without any visible alert in your billing dashboard.
What's the difference between Slicker's retry engine and the built-in retry settings in Stripe Billing or Chargebee?
Billing platform built-in retry settings apply a fixed schedule uniformly across your subscriber base, reading gateway response codes and applying a rule without MAC-level routing or hour-level timing precision. Slicker's AI engine weighs over 40 variables per transaction, including card type, issuer behavior, regional payday calendars, and MAC signals, to determine whether to retry, when exactly to retry, and on which payment method. The two approaches can run in parallel, with AABB testing measuring the dollar difference between them on your own traffic before any financial commitment.
What tools should a SaaS CFO use to recover lost revenue from failed payments in 2026?
The starting point is separating the problem into two categories: failures that resolve without customer involvement (soft declines recoverable through well-timed retries) and failures that require customer action (stolen or expired cards requiring dunning outreach). For the first category, a dedicated retry engine that reads decline codes, honors MAC instructions, and times attempts to payday windows will outperform any billing platform's out-of-the-box retry settings. For the second, dunning emails sent from your own domain with failure-specific messaging outperform generic "update your payment method" sequences. The measurement question matters as much as the tooling: a controlled test measuring dollars recovered per group with statistical significance is the only defensible way to know whether a given tool is adding incremental lift over your billing platform's baseline.
Can you recover failed Zuora or Recharge payments without engineering resources?
Yes, for both. Slicker connects to Zuora and Recharge through a no-code integration requiring only API credentials, with zero engineering lift on your side. The Zuora path adds a two-phase process: sandbox validation first, then production deployment, because Zuora's data model requires smoke checks before going live. All recovered payments flow through your existing Zuora or Recharge billing rails and appear in your native reporting exactly as regular payments would.
Related Articles
Failed Payments as a Board-Level Revenue KPI (Oct 2026)
Failed payment recovery tends to live in finance ops reviews, not board decks. That's usually because it's reported as a process metric and not a revenue...
Building a Recovery Layer Above Chargebee Without Disrupting Billing September 2026
Failed payments in Chargebee don't all fail for the same reason, but Chargebee's native retry logic largely treats them that way. The result is burned retry...
CFO-Grade Failed Payment Recovery ROI Model Oct 2026
There's a revenue number sitting inside your billing data that most finance teams never model correctly. It's the incremental lift from better payment...
Stop losing revenue to failed payments
Join leading subscription businesses using Slicker to recover failed payments automatically.
Get Started