Where 20% More Payment Recovery Comes From (Sep 2026)
A 20% recovery uplift sounds like a headline until you try to figure out what it actually means for your baseline. Relative improvement, absolute percentage points, incremental dollars above what your existing system already captures: these are three different numbers, and only one of them belongs in a business case. This post walks through where the real lift comes from and how to measure it against your own data.
TLDR:
- Roughly 15% of recurring card transactions are declined, and failed payments drive ~50% of involuntary churn, per PYMNTS data.
- "20% recovery uplift" can mean relative or absolute improvement; your starting baseline determines which number actually matters for your MRR.
- Soft declines make up 80-90% of failed card-not-present payments and are retryable; hard declines are permanent, and retrying them damages your MID (merchant ID) reputation and triggers network penalties.
- Smart retry timing outperforms retry frequency: industry benchmarks show 70-85% recovery on recoverable soft declines versus 40-60% for fixed schedules.
- Slicker's AABB testing methodology measures incremental dollars recovered above your existing baseline with p-values; if Slicker does not outperform your control with statistical significance, you do not pay.
The Scale of the Problem: Why Failed Payments Drain Subscription Revenue
Roughly 15% of recurring card transactions are declined, per industry data. For a subscription business doing $10M in annual revenue, that failure rate is a structural leak that compounds every billing cycle.
Most of it is invisible. Customers whose cards expired or funds ran short did not choose to leave. They are pushed out by payment infrastructure, a phenomenon known as involuntary churn, which accounts for 20 to 40% of all subscription cancellations. These are customers who already said yes, whose acquisition cost is already spent.
The math moves fast. Failed payments drive about 50% of involuntary subscription churn, per PYMNTS data cited by Beast Insights. A 20% recovery uplift does not require a 20% reduction in failures overall; it requires recovering more of the failures that were always recoverable to begin with, protecting subscription recovery rate and MRR (monthly recurring revenue) that no marketing campaign can replace.
Understanding What "20% Recovery Uplift" Actually Means
When vendors say "20% more payments recovered," two very different numbers can hide behind that claim.
The first is a relative improvement. If your current retry logic recovers 50% of failed payments and a smarter system recovers 60%, that is a 20% relative increase, even though the absolute improvement is only 10 percentage points. The second is an absolute lift, measured in percentage points directly. A 4 to 10 percentage-point improvement is what we mean at Slicker when we describe absolute recovery-rate uplift, and those two figures are not interchangeable.
Why does this matter to a CFO building an internal business case? The baseline you start from determines everything. A business recovering 30% of failed payments today has far more headroom than one already at 70%. A 20% relative improvement applied to a 30% baseline gets you to 36%; applied to a 70% baseline, it gets you to 84%. The same headline number, two very different revenue outcomes.
The credible way to assess any uplift claim is to measure incremental dollars recovered above your existing baseline, using your own transaction data, with statistical controls: that is the core premise behind smart dunning versus rules-based recovery that separate the vendor's contribution from what your current system would have recovered anyway. That is what a properly structured A/B test produces, and it is the only number worth putting in a board deck.
Soft Declines vs. Hard Declines: The First Branching Point
Correct failure classification is the branching point every recovery decision flows from. Get it wrong and the rest of the strategy falls apart.
Soft declines are temporary. Insufficient funds, network timeouts, processor errors: the card is valid, the customer relationship is intact, and a well-timed retry can recover the payment without any customer involvement. Soft declines make up 80-90% of failures in subscription businesses, so the majority of your failure volume is retryable in principle.
Hard declines are permanent. A stolen card, a closed account, a fraud flag: no retry will change the outcome. Retrying anyway burns attempts from your card network allocation, signals poor authorization behavior to issuers, and triggers penalties. Mastercard charges $0.10 per attempt when a merchant retries after receiving MAC (Merchant Advice Code) 03 (Do Not Try Again), and those costs accumulate quickly at volume.
The complication is that the same gateway code can mean different things depending on what sits beneath it. A "do not honor" response paired with MAC 26 means retry after two days. The same response paired with MAC 03 means stop entirely. A retry engine that reads only the gateway error code and ignores network-layer signals will misclassify these across thousands of transactions per month. The result: wasted retry budget on unrecoverable cards and abandoned revenue on recoverable ones.
Why Retry Timing Outperforms Retry Frequency
More retries feel like more chances. In practice, firing attempts on a fixed schedule often means hitting the same empty account multiple times before the billing window closes.
The issue is timing alignment. An insufficient funds decline on a consumer debit card in the US has a predictable recovery window: intelligent payday retries scheduled around payroll deposit clearing times recover revenue that a midday attempt misses entirely. The card is valid. The funds arrive. The retry just has to be there when they do.
Smart retry systems consistently reach 70 to 85% recovery on recoverable failed payments, compared to 40 to 60% for fixed retry schedules. That gap is explained by whether attempts land when authorization probability is highest, which requires reading card type, issuer behavior, and geography instead of relying on a calendar.
Excessive retries on a fixed schedule also carry a direct cost. Visa and Mastercard retry caps per month per card within a 30-day window, with escalating penalties for violations. A schedule that fires frequently without timing intelligence burns through that allocation on low-probability windows, leaving fewer compliant attempts available for the moments that actually convert.
The 40-Variable Problem: What a Fixed Retry Schedule Cannot See
Each failed payment has its own story. A fixed retry schedule ignores that entirely, applying the same wait-then-retry logic to a consumer debit card in rural Ohio and a corporate Amex in London. That is the core problem with batch payment retries regardless of issuing bank, transaction size, or payday timing.
Slicker's retry engine weighs over 40 variables per transaction before scheduling an attempt, including:
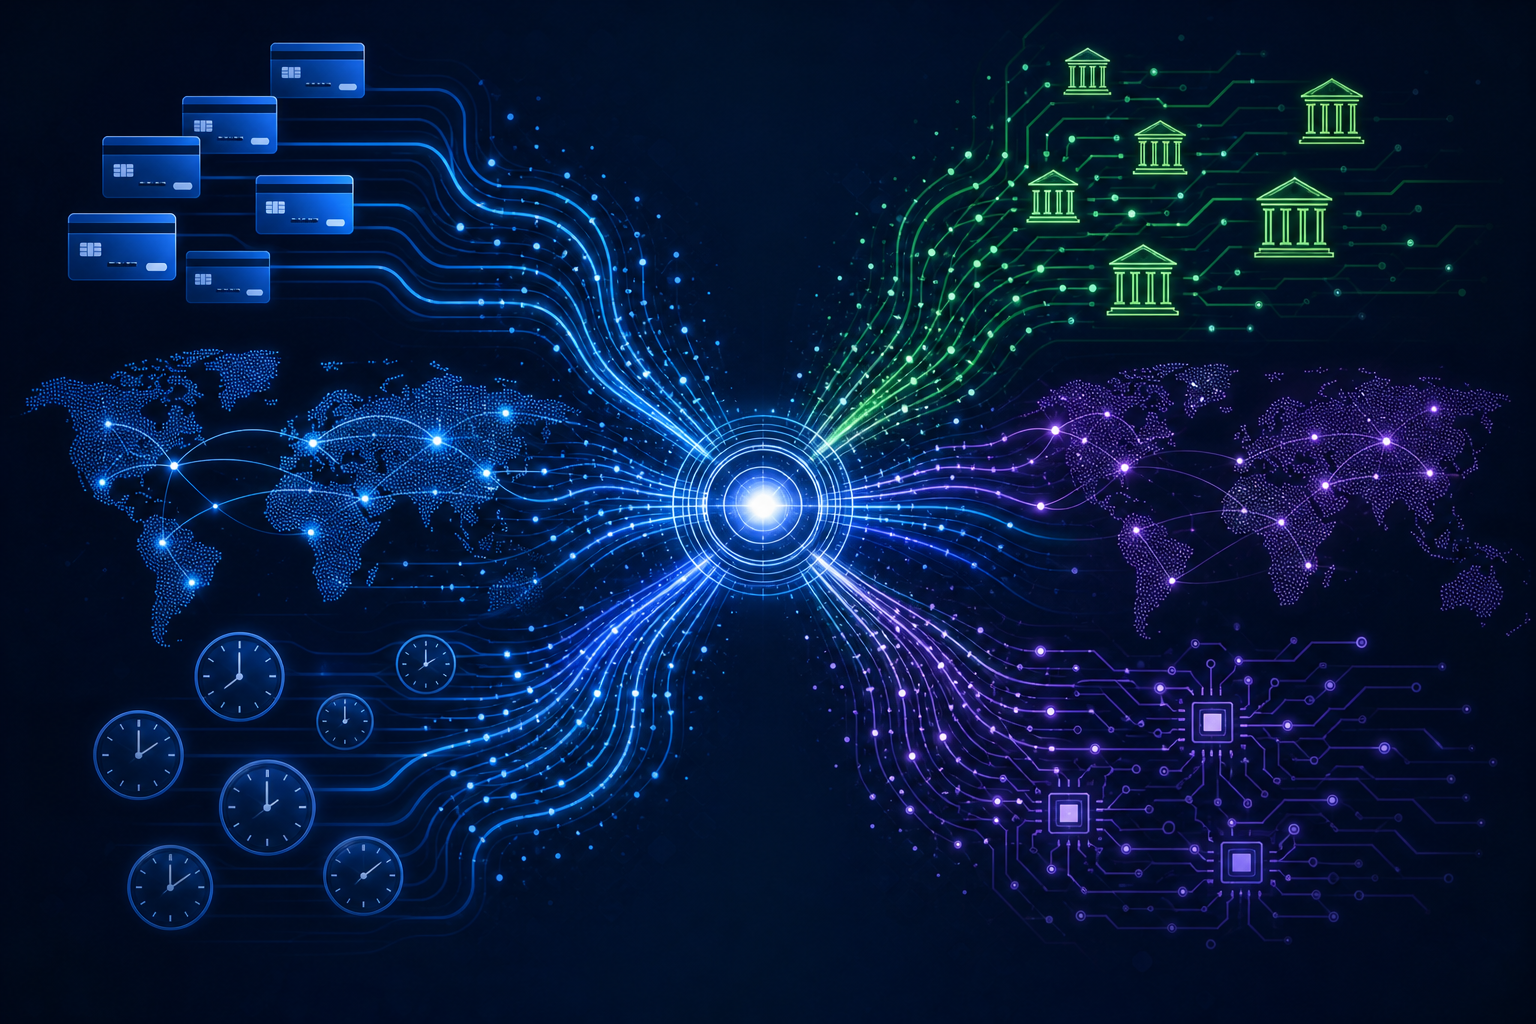
- Card type and issuer behavior: consumer debit cards authorize differently than credit or prepaid instruments, and individual issuing banks have distinct authorization patterns around payroll windows and overnight processing cycles.
- BIN data: the first six to eight digits of a card number identify the issuing bank and product type, giving the model issuer-specific intelligence before a single retry fires.
- Geographic payday cadence: US subscribers on biweekly pay cycles have different peak fund-availability windows than UK subscribers paid monthly or Australian subscribers paid weekly.
- Time-of-day signals: a retry at 12:01am on a US payday hits a materially different authorization environment than the same retry at 2pm.
- Subscriber payment history: a customer with 18 months of on-time payments who hits one insufficient funds decline is a different recovery case than a first-cycle subscriber with the same code.
Rules apply fixed logic to groups. Each failed payment in Slicker gets its own analysis, scored against its own signal set, with retry timing set to the window where authorization probability is highest for that specific card and issuer. That per-transaction precision is where the recovery rate uplift comes from.
How Merchant Advice Codes (MACs) Shape Retry Decisions
Merchant Advice Codes give retry logic something a calendar never can: a per-transaction instruction from the issuer telling you exactly what to do next.
The codes that matter most in a recovery context are MAC 03, MAC 21, and the time-specific series from MAC 24 through MAC 30. MAC 03 (Do Not Try Again) is a hard stop. Retrying after receiving it triggers a $0.10 penalty per attempt under Mastercard's excessive authorization rules, and at volume those fees compound into a material cost. MAC 21 (Stop Recurring Payment) signals a cardholder-initiated cancellation, not a temporary hold. Any further retry violates both network rules and the customer relationship.
MAC Code | Issuer Instruction | Retry Action | Wait Period |
|---|---|---|---|
MAC 03 | Do Not Try Again | Hard stop: no further retries | Never |
MAC 21 | Stop Recurring Payment | Cardholder-initiated cancel: cease all retries | Never |
MAC 24 | Retry after 1 hour (Mastercard use only) | Retry after prescribed wait | 1 hour |
MAC 25 | Retry after 24 hours (Mastercard use only) | Retry after prescribed wait | 24 hours |
MAC 26 | Retry after 2 days (Mastercard use only) | Retry after prescribed wait | 2 days |
MAC 27 | Retry after 4 days (Mastercard use only) | Retry after prescribed wait | 4 days |
MAC 28 | Retry after 6 days (Mastercard use only) | Retry after prescribed wait | 6 days |
MAC 29 | Retry after 8 days (Mastercard use only) | Retry after prescribed wait | 8 days |
MAC 30 | Retry after 10 days (Mastercard use only) | Retry after prescribed wait | 10 days |
The time-specific codes prescribe exact waiting periods: MAC 24 after one hour, MAC 25 after 24 hours, MAC 26 after two days, MAC 27 after four days, MAC 28 after six days, MAC 29 after eight days, and MAC 30 after ten days. A retry engine that reads these correctly aligns attempts to issuer-approved windows instead of firing blindly.
The practical complication is the dunning-deadline conflict. If your billing grace period closes in five days and a MAC instructs you to wait ten, following the code strictly means missing the recovery window entirely. Smart retry logic treats MACs as a weighted input, not an absolute rule, finding the highest-probability attempt within the remaining dunning window. Compliance is the floor; recovery probability determines where within the compliant range the attempt fires.
The Revenue Cost of Retrying Hard Declines
Retrying a hard decline feels like persistence. What it actually does is erode the infrastructure every future payment depends on.
When a merchant repeatedly attempts charges after receiving hard decline signals, card networks log that behavior. A degraded merchant ID (MID) reputation lowers authorization rates across all transactions, including first-time customer-initiated payments, which is one of the less-visible hard decline retry penalties that compound over time. The subscriber you were trying to recover ends up costing you approvals on net-new customers.
The monetary penalties are direct. Mastercard charges $0.10 per retry on MAC 03 transactions, and broader excessive authorization rules introduced in 2026 apply stricter oversight with penalties that escalate with volume. At scale, undisciplined retry logic generates a measurable cost line that offsets recovered revenue.
A billing system that has been retrying hard declines aggressively for months also arrives at any smart retry evaluation with a depressed authorization rate. Stopping hard decline retries is often the fastest way to lift overall authorization rates before any AI optimization layer touches the recoverable soft decline pool.
The Role of Dunning as a Fallback, Not a First Line
Silent recovery comes first. If a retry can resolve the failure without the customer ever knowing a payment failed, that is the right path: no email to write, no friction for the subscriber, no risk of alarming someone who had a momentary funds shortfall.
Dunning enters only when the failure reason demands it. An expired card cannot be retried into authorization. A stolen card requires the customer to contact their bank. A cancelled mandate in Germany needs explicit customer action to reinstate. These failures have a structural ceiling on automated recovery, and an email is the only viable next step.
What that email says matters as much as when it arrives. Failure-reason-specific messaging tells the customer exactly what happened and exactly what action resolves it. The email for an expired card looks different from the one triggered by a stolen card, which looks different again from an RBI pre-debit notification failure in India.
One pattern that consistently creates problems is tying dunning cadence to smart retries in a 1:1 ratio. That structure treats every attempt as a customer-facing event, generates inbox noise for failures the retry engine may well resolve on its own, and teaches subscribers to ignore recovery communications entirely. Decoupling email cadence from retry cadence preserves the channel for the moments it actually converts.
Measuring Real Uplift: Why Attribution Methodology Determines Whether the Number Is Credible
Without a control group, there is no credible answer. A billing system that already runs native retries will recover a share of failed payments on its own. If a second tool runs on top of it, every recovery gets attributed to the tool, regardless of whether it contributed anything incremental. The reported number is real revenue. The claimed credit is not.
A properly structured test splits failed payments into two cohorts: one processed by the existing system, one by the new logic, running simultaneously on comparable transaction mixes. The metric that matters is dollars recovered per group. Counting transactions inflates performance when a single invoice generates multiple retry attempts, each registering as a separate event in aggregate reporting.
Statistical significance determines whether the difference reflects actual performance or noise. A p-value below 0.05 across 10,000 transactions is a result you can take to a board. The same three-point gap across 200 transactions tells you almost nothing.
The credible number is incremental dollars recovered above what your baseline system would have produced alone, measured on your own data, with controls that hold across the test period.
How Slicker Produces and Proves the 20% Uplift
The uplift comes from stacking multiple levers correctly: classifying failures before retrying, timing attempts against issuer-specific authorization windows, reading Merchant Advice Codes (MACs) as weighted inputs and not absolute rules, and routing across payment methods when the original instrument is exhausted.
Slicker's retry engine weighs over 40 variables per transaction. In documented tests, the control group averaged 4.4 retry attempts per failed payment; Slicker averaged 6.1 while recovering materially more revenue. Fewer wasted attempts on hard declines, better-timed attempts on soft declines, and compliance guardrails that protect your MID reputation.
What matters is the incremental dollars recovered above what your existing system would have produced, measured on your own data. That is exactly what our AABB testing methodology produces. Borrowed from clinical crossover trial design, it splits your failed payment volume into stratified cohorts, runs Slicker against your current logic simultaneously, and reports recovered dollars per group with p-values and confidence intervals. If Slicker does not outperform your control with statistical significance, you do not pay.
The 4-month pilot, with the first month free, is built around that proof requirement. Results surface before billing begins.
Final Thoughts on Proving Payment Recovery Uplift With Your Own Data
A 20% uplift claim means nothing without a control group, your own transaction data, and statistical significance. The concepts here, from MAC-aware retry logic to timing against payday windows, only matter if they produce incremental dollars above what your current system already recovers. Getting that answer takes a properly structured test, not a vendor promise. Talk to us about running one on your data before any billing begins.
FAQs
How does Slicker's AI-powered retry timing differ from a static retry schedule?
A static retry schedule fires on fixed calendar intervals regardless of card type, issuing bank, or geography. Slicker's retry engine weighs over 40 variables per transaction, including payday cadence by region, issuer-specific authorization patterns, time-of-day signals, and BIN data, to identify the highest-probability recovery window for that specific card. A US consumer debit card with an insufficient funds decline, for example, is most likely to authorize at 12:01am when payroll deposits clear, not midday when a fixed schedule might fire.
What is the difference between relative and absolute payment recovery improvement, and which number should go in a board deck?
A relative improvement compares your new recovery rate to your old one as a percentage change: moving from 50% to 60% recovery is a 20% relative uplift. An absolute lift measures the direct percentage-point gain: that same move is a 10-point improvement. For board-level business cases, incremental dollars recovered above your existing baseline, measured on your own transaction data with a statistically verified control group, is the only credible figure. Relative uplift headlines can look compelling while masking a modest absolute gain, depending on where your baseline sits.
How does Slicker compare to Stripe Smart Retries, Butter Payments, and Churn Buster?
Stripe Smart Retries couples dunning emails 1:1 with retry attempts, sends Stripe-branded communications, and cannot separate retry cadence from email cadence. Butter focuses primarily on card updater services and requires engineering involvement to set up. Churn Buster offers strong dunning email campaigns but has limited retry intelligence and no gateway routing. Slicker combines AI-powered retry timing, failure-reason-specific dunning, and multi-gateway routing into one system, with each component configurable independently, and proves incremental lift through AABB testing with statistical significance before any payment is required.
How do you measure whether a recovered payment was genuinely incremental versus self-recovered by your existing system?
Without a concurrent control group, every recovery gets attributed to whichever tool ran last, regardless of whether it contributed anything. Slicker's AABB testing methodology measures exactly that gap. See the Measuring Real Uplift section above for the full cohort design, dollar-per-group metric, and statistical requirements.
How do I set up smart payment retries without any engineering work for my subscription business?
Connecting Slicker to supported billing platforms, including Stripe Billing, Chargebee, Recurly, Zuora, and Recharge, requires only API keys from your billing platform and payment provider, entered directly into the Slicker dashboard. No code changes, no developer time, and no modifications to your existing payment infrastructure are required. Payment credentials never leave your existing PCI-compliant systems; Slicker provides optimization intelligence and retry timing instructions while all charges continue to execute through your current payment rails.
Related Articles
Build vs Buy: Payment Retry Logic Deep Dive (September 2026)
Your engineering team can build retry logic. The harder question is whether they should. The gap between a basic retry schedule and something that actually...
2026 Revenue Recovery Playbook for Subscription Businesses
Failed payments are responsible for somewhere between 20 and 40% of subscription churn across the industry. Those subscribers never chose to leave. A good...
Retry Old Card or Wait for CAU? A Sep 2026 Guide
Card account updater retry logic sounds straightforward until you're staring at a mixed queue of expired cards, insufficient funds declines, and closed...
Stop losing revenue to failed payments
Join leading subscription businesses using Slicker to recover failed payments automatically.
Get Started