2026 Revenue Recovery Playbook for Subscription Businesses
Failed payments are responsible for somewhere between 20 and 40% of subscription churn across the industry. Those subscribers never chose to leave. A good revenue recovery strategy is what quietly wins them back before your billing system ever cancels the account, and this playbook breaks down exactly how that works.
TLDR:
- 20 to 40% of subscription churn traces back to failed payments, not cancellation decisions; your retention playbook cannot fix a billing problem.
- Classify declines before retrying: soft declines are recoverable with smart timing; retrying hard declines triggers network penalties and damages your merchant account.
- The recovery sequence is smart retries first, card account updater second, dunning only when customer action is the only path forward.
- A $5M MRR business with 1.5% involuntary churn loses roughly $900k annually to subscribers who never chose to leave.
- Slicker splits failed payments 50/50 against your existing retry logic using AABB testing; if it does not outperform with statistical significance, you pay nothing.
What Is Revenue Recovery for Subscription Businesses?
Revenue recovery, in the subscription context, is the set of processes a business uses to recapture recurring revenue lost not because a customer chose to leave, but because a payment failed. A subscriber whose card was declined for insufficient funds never made a cancellation decision. Neither did one whose card expired between billing cycles. These are not voluntary cancellations, and treating them that way means applying the wrong playbook.
Two distinct mechanisms are involved. The first is automated: smart retry logic that re-processes a failed charge at the right time, without any customer involvement. The second is customer-facing: targeted outreach asking the subscriber to take a specific action, such as updating an expired card, when automation alone cannot resolve the failure.
Revenue recovery is also not debt collection. There is no dispute, no delinquency, and typically no dissatisfaction. The customer still wants the product. The job is simply to reconnect a willing subscriber to a functioning payment method before the billing system cancels the account.
The Scale of the Problem: How Much Is at Stake
Failed transactions were projected to cost subscription companies $129 billion in 2025. At company scale, that looks like this: a business running $10M ARR with 5% monthly churn loses $1 to $2 million annually to involuntary churn alone, based on industry data suggesting 1 to 2 percentage points of that churn trace back to payment failures.
Across subscription businesses, 20 to 40% of total churn comes from failed payments, not deliberate cancellations. These subscribers would have renewed. The revenue was already earned before it walked out the door.
Why Payments Fail: Soft Declines vs. Hard Declines
Not every failed payment is the same problem. Before any recovery strategy makes sense, you need to understand why the failure happened, because the answer changes everything about what to do next.
Soft Declines vs. Hard Declines
Soft declines are temporary: insufficient funds, network timeouts, processor errors. The card is valid and the customer relationship is intact. Retry at the right time and the payment will likely clear. Hard declines are permanent. A stolen card, a closed account, or a fraud flag means no retry will succeed; the only path forward requires cardholder action.
Factor | Soft Decline | Hard Decline |
|---|---|---|
Nature | Temporary | Permanent |
Common causes | Insufficient funds, network timeout, processor error | Stolen card, closed account, fraud flag |
Card validity | Card is valid; customer relationship intact | Card is invalid or blocked |
Retry outcome | Likely to clear with correct timing | Will not succeed regardless of timing |
Recovery path | Automated smart retry (silent) | Customer action required (new card/method) |
Retry penalties | None when limits are respected | Mastercard charges $0.10/attempt after "Do Not Try Again" code; Visa caps at 15 attempts/30 days |
Share of failures | ~80-90% of failed payments | ~10-20% of failed payments |
Retrying a soft decline at the right moment recovers revenue. Retrying a hard decline wastes attempts and carries real penalties. On the Mastercard network, Merchant Advice Code 03 ("Do Not Try Again") is a hard stop: retrying after receiving it triggers a $0.10 penalty per attempt. Visa operates a separate retry-limit framework, and it does not publish a comparable Merchant Advice Code set, capping retries at 15 attempts within 30 days per card; exceeding that threshold can damage your merchant account's authorization reputation across all transactions, including first-time ones.
The deeper complication: some of the most common decline codes are ambiguous. A "do not honor" response can be a soft decline in one context and a hard one in another, depending on the network and advice codes that accompany it. Getting the classification wrong in either direction has costs. Miss a recoverable failure and you lose revenue; push a hard decline through retry logic and you accumulate penalties. Accurate failure classification is the prerequisite for every recovery decision that follows.
Involuntary Churn vs. Voluntary Churn: Why the Distinction Matters
Voluntary churn and involuntary churn share a symptom: a subscriber stops paying. Everything else about them is different.
Voluntary churn is a decision. The customer weighed the product against the price and chose to leave. Winning them back requires product changes, pricing adjustments, or a well-timed cancellation-flow offer. Involuntary churn is a billing event. A card declined for insufficient funds or an expired card on file ended the subscription with no intent from either side.
Conflating the two causes RevOps and retention teams to spend budget on the wrong interventions, compounding the hidden cost of failed payments. A win-back campaign aimed at a subscriber pushed out by a soft decline treats a payments problem as a product problem. Discount-led save flows and exit surveys never reckon with what actually happened: a failed transaction the subscriber was never aware of.
Recovery from involuntary churn lives in the billing and payments layer. The fix is either an automated retry that silently recaptures the payment before the account cancels, or targeted outreach asking the customer to take a specific payment action. Routing involuntary churn through retention tooling means solving a card-network problem with a customer-satisfaction playbook, and the math will never work.
For revenue operations teams allocating budget, the distinction is a clean filter: identify what share of churn traces back to payment failures, separate that cohort, and assign it to payment recovery infrastructure instead of retention spend.
The Three Pillars of a Subscription Revenue Recovery Strategy
A recovery strategy is only as strong as its sequencing. Three levers exist, and the order in which you deploy them determines whether you recover revenue quietly or burn subscriber goodwill in the process.
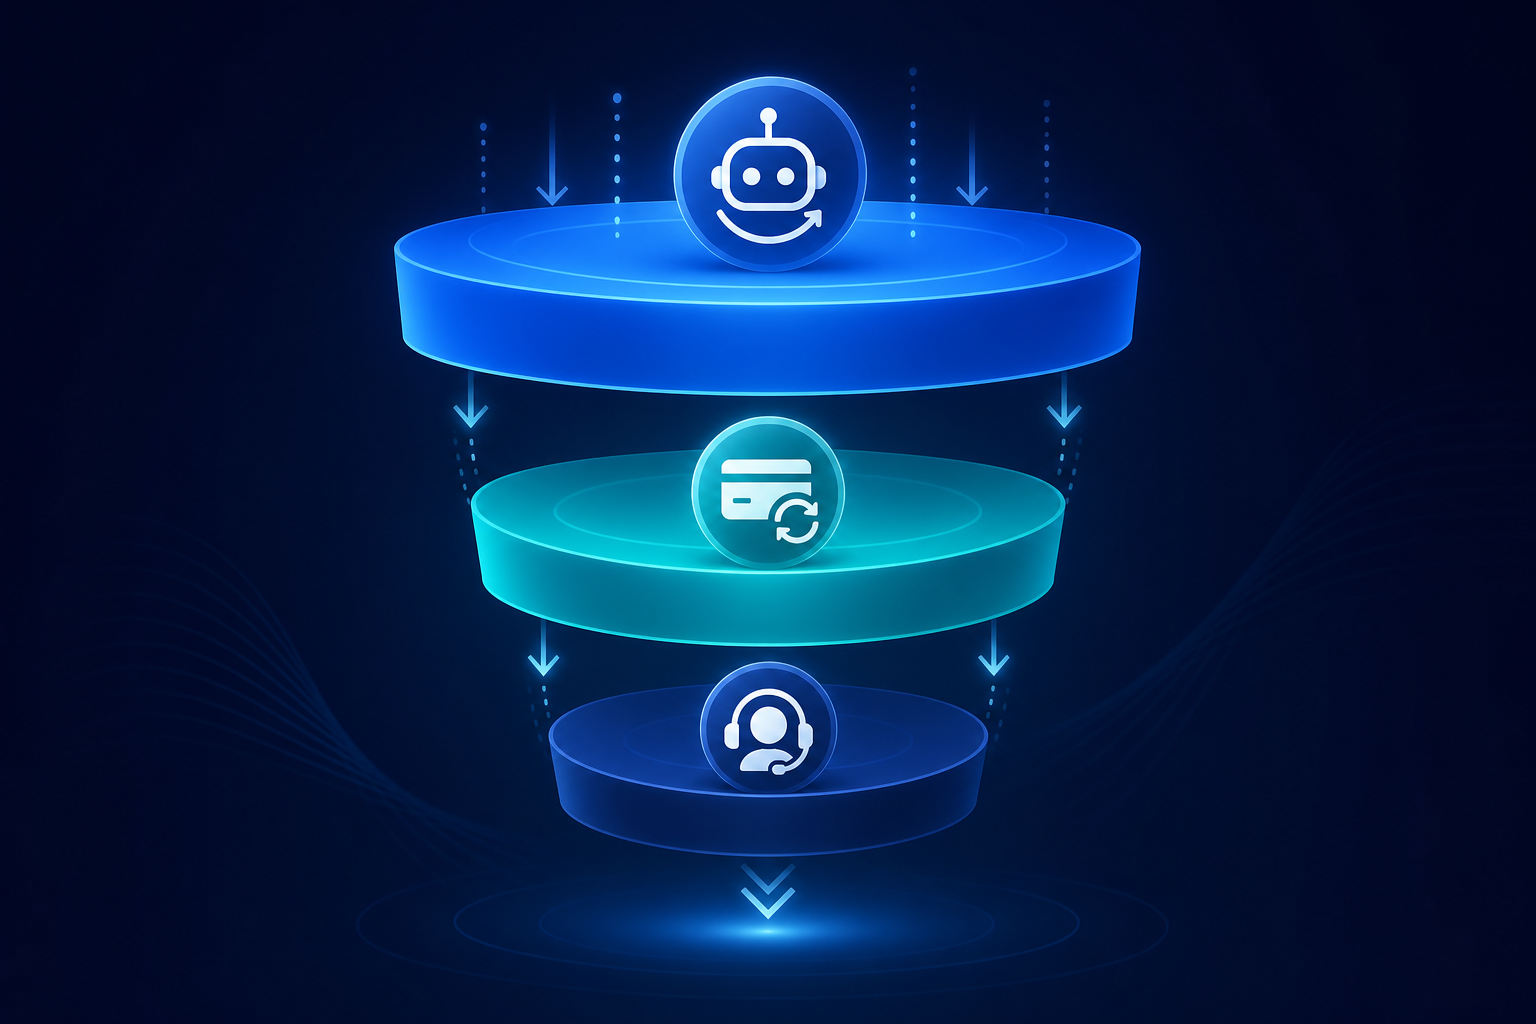
Smart payment retries come first. When a soft decline hits, the goal is to recover the payment without the customer ever knowing there was a problem. Retry at the right moment and the transaction clears silently: the subscriber keeps access, no email is sent, nothing disrupts the relationship.
Account updater services sit alongside retries as the second layer of silent recovery. Card credentials expire or get reissued constantly, so an account updater syncs stored card details automatically against network databases before a failure even occurs.
Dunning communications are the third pillar, deployed only when the first two cannot resolve the failure. A stolen card will never succeed on retry. An expired card missed by the account updater requires the subscriber to provide a new one. In those cases, targeted outreach is the right move, but the message must reflect the specific failure reason, not a generic "update your payment method" prompt.
Silent recovery comes first; customer contact only when required. Businesses that lead with dunning emails for every payment failure waste subscriber attention on problems that retries would have resolved automatically, and that attention is finite.
Smart Payment Retries: Timing, Frequency, and Failure Classification
Static retry schedules fire on a fixed calendar regardless of why a payment failed. A card declined for insufficient funds on a Tuesday behaves nothing like one flagged for suspected fraud, but a fixed schedule treats them identically.
Soft declines are 80-90% of failed payments in subscription businesses, and most are recoverable if retried at the right moment. Adaptive retry systems read decline codes, apply Merchant Advice Codes (MACs), and align attempts to signals like payday cycles and time-of-day fund availability. Consumer debit cards in the US, for instance, are most likely to authorize at 12:01am when payroll deposits clear, a pattern that drives intelligent payday retry scheduling. Smart retry systems consistently recover 70 to 85% of soft declines; fixed schedules land between 40 to 60%.
Network limits matter too. Visa caps retries at 15 attempts within 30 days per card. Exceeding those thresholds triggers penalties and, at scale, damages your merchant account's authorization reputation on all transactions going forward. Timing precision protects both recovery rates and compliance standing.
Account Updater Services: Preventing Failures Before They Happen
Up to 33% of payment credentials change annually through card expiry, reissues after loss or theft, and fraud replacements. Each change is a renewal that can fail before anyone notices.
Card account updater (CAU) services, offered by Visa (Visa Account Updater) and Mastercard (Mastercard Automatic Billing Updater), automatically sync stored card details against network databases before a charge attempt goes out. The failure never happens because the credentials are already current.
CAU handles one specific failure class: stale credentials. Valid cards with sufficient funds that still decline due to network timeouts, processing errors, or bank-side friction require retry logic to recover. Without an account updater, a share of your retry attempts will always fire against credentials that were never going to authorize regardless of timing.
Dunning Communications: When and How to Reach Out
Dunning makes sense only when customer action is the only path forward. If a soft decline is retryable, send the retry. If account updater can refresh the credentials, let it. Outreach enters the picture when automation cannot resolve the failure on its own: a stolen card the subscriber must replace, an expired card the network missed, a cancelled payment mandate that needs reinstating.
Failure-reason dunning cadence is what separates useful dunning from noise. A subscriber whose card was flagged as stolen needs to hear that they should contact their bank and add a new payment method. Sending both that subscriber and one with a simple expired card the same generic "we couldn't process your payment" message increases friction and reduces the chance either completes the required action.
The email should come from your domain, not a third-party vendor domain. A recovery email from an unfamiliar sender looks like phishing, and brand trust is part of the conversion path. Messages framed around what the subscriber stands to lose ("your access to X will be paused") consistently outperform transactional language ("your payment of $X was declined"). The first is a service-continuity prompt; the second just reports a billing event.
Dunning Cadence and Grace Period Optimization
Grace period decisions force a real tradeoff. Every day you extend the dunning window, you give a failed payment another chance to recover, while a subscriber continues consuming your service without generating revenue. At scale, that cost compounds fast.
Recovery rates drop sharply after day 21; the third week (days 14 to 21) captures a small but meaningful share of recoveries, and extending the window beyond that mostly adds service cost without proportionate gains. Three weeks captures the meaningful recovery curve; extending beyond it mostly adds service cost.
That said, three weeks is a default, not a rule.
Matching Grace Periods to Subscriber Risk
The right window depends on your subscriber mix. High-tenure subscribers with long payment histories are worth a longer, more patient recovery sequence, while first-time payers or promotional cohorts with thin history warrant faster escalation. Configuring distinct grace periods by subscriber tenure, prior billing cycles, and country of origin lets you match recovery aggressiveness to the commercial value and risk profile of each cohort.
Retry aggressiveness should also shift as the window progresses: early-phase retries can be spaced further apart, tightening as the grace period approaches its end. Testing shorter versus longer dunning windows across statistically comparable cohorts is the only reliable way to find your actual optimization point, not guess at it.
Key Revenue Recovery Metrics Every Subscription Business Should Track
Tracking recovery performance requires the right unit of analysis. The most common mistake is measuring at the transaction level, counting each payment attempt as a separate recovery event. A single invoice that resolves after three retry attempts can surface as three recovered transactions, inflating your recovery numbers and obscuring what actually happened. Invoice-level tracking is what matters: how many unique failed invoices moved from unpaid to recovered.
With that framing in place, here are the metrics worth monitoring:
- Initial failure rate: the percentage of recurring charges that fail on the first attempt, before any retry logic fires. This is your baseline exposure.
- Recovery rate: recovered invoices divided by total failed invoices. Track this separately for soft declines and hard declines, since aggregating them produces a number that is hard to act on.
- Net involuntary churn rate: the share of subscribers lost specifically to payment failures after all recovery attempts have completed.
- Time-to-recovery: the median number of days between initial failure and successful payment. Faster recovery means shorter service disruption windows.
- MRR protected: translates recovered invoices into a metric that finance and executive stakeholders actually track.
Involuntary churn benchmarks by vertical vary by subscriber acquisition mix. Promotional cohorts fail at two to three times the rate of organic subscribers. Your own historical recovery rate, segmented by failure type and acquisition source, is a more reliable performance anchor than any industry average.
How to Build the Internal Business Case for Revenue Recovery Investment
Building the business case starts with your own numbers, not an industry benchmark.
Estimate your revenue at risk in three steps: take your MRR (monthly recurring revenue), multiply by your involuntary churn rate (typically 1 to 2 percentage points of total monthly churn for most subscription businesses), and you have a monthly leak figure. Annualize it. For a $5M MRR business with 1.5% involuntary churn, that is $900k walking out the door annually from customers who never decided to leave.
Frame the cost of inaction clearly for finance stakeholders: every month without a recovery investment is a month of compounding loss on already-earned revenue. Performance-based pricing, where you pay only on recovered revenue, converts an uncertain budget line into a self-funding initiative with a calculable return from day one.
A CFO pitched by three vendors in the past year is rightly skeptical of benchmark claims. The strongest internal business cases rest on your own historical transaction data: your actual failure rate by decline type, your current recovery rate by failure category, and a clear delta showing what incremental lift would be worth in dollars.
If you already have retry logic running, the relevant metric is incremental recovery above your existing baseline. Claiming credit for payments your current system would have recovered anyway is noise, not a business case.
Multi-Gateway Routing and Payment Orchestration as a Recovery Layer
Not every decline is a cardholder problem. Gateway-specific issues present distinct failed payment recovery challenges: regional downtime, processor misconfigurations, issuer relationships that favor one acquirer over another can reject a perfectly valid card that would have authorized through a different route. Retrying through the same processor that issued the original decline often just replicates the same failure.
Multi-gateway routing works by analyzing each failed payment against gateway performance data, geography, and transaction context before selecting which processor to send the retry through. A transaction declined by one processor due to a regional outage or authorization bias can clear through a secondary gateway without any change to the cardholder's account.
This recovery layer is distinct from retry timing optimization. Timing improvements maximize the probability of success on a given gateway. Routing intelligence changes the gateway itself, opening a recovery path that pure retry logic cannot reach.
How Slicker Approaches Revenue Recovery for High-Volume Subscription Businesses
Slicker builds each layer of the recovery playbook into a single system, then proves the results before you pay for them.
The retry engine analyzes over 40 variables per transaction: card type, issuing bank, BIN data, geographic region, local payday cadence, and time of day. It runs an ensemble of AI models, each specialized by geography, issuer behavior, and failure type. Smart retry systems consistently recover 70-85% of soft declines; fixed retry schedules typically land between 40-60%. Dunning emails follow only when customer action is genuinely required, sent from your domain with messaging tied to the specific failure reason.
The differentiator for enterprise buyers is how performance gets verified. Slicker uses AABB testing in payment recovery, a methodology borrowed from clinical trial design, splitting failed payments 50/50 between your existing retry logic and Slicker's. The test measures dollars recovered, reports statistical significance, and if Slicker does not outperform with that significance, you do not pay. Your own transaction data is the proof.
Setup takes under 5 minutes with zero engineering lift on Stripe Billing, Chargebee, Recurly, Zuora, and Recharge. Slicker's 4-month pilot (first month free, three paid months, cancel anytime) is priced as a percentage of recovered revenue with no upfront costs, making the investment self-funding from the first recovered invoice.
Final Thoughts on Stopping the Revenue Leak in Subscription Billing
Recovering involuntary churn is a billing problem with a billing solution. Get the failure classification right, run retries before you run outreach, and match your dunning cadence to the actual risk profile of each subscriber cohort. The math on what you are leaving behind each month is worth running. Connect with Slicker to run it on your own numbers.
FAQs
How does AI-powered payment retry logic work for subscription businesses?
AI-powered retry logic classifies each failure as a soft or hard decline, then analyzes signals like card type, issuing bank, geographic payday cadence, and time of day to determine whether to retry, when, and how many times. Smart retry systems that read these signals consistently recover 70 to 85% of soft declines, compared to 40 to 60% for fixed retry schedules that fire on a calendar regardless of failure reason. The core difference is per-transaction decision-making: each failed payment gets its own analysis instead of being assigned to a rule that applies uniformly across a segment.
What KPIs should a SaaS revenue operations team track to measure involuntary churn recovery?
Aggregating recovery counts at the transaction level instead of the invoice level is the most common measurement error. Track at invoice level, not attempt level, to get accurate recovery rates.
What subscription payment recovery platforms work with Stripe, Adyen, and Braintree?
Slicker supports all three, along with Checkout.com, PayPal, Worldpay, Cybersource, and Authorize.net on the payment provider side, paired with billing systems including Stripe Billing, Chargebee, Recurly, Zuora, and Recharge. Setup requires connecting both the billing system and the payment service provider: billing-system-only integration limits the depth of error classification and retry-timing intelligence available, so both connections are treated as prerequisites for full recovery coverage.
How does delta-based pricing work, and why does it matter for businesses that already recover some failed payments?
Delta-based pricing charges only on recoveries above your existing baseline, so you pay for incremental lift and not for payments your current system would have recovered anyway. This matters because claiming credit for the full recovery volume, including what rule-based retry logic was already capturing, inflates the apparent return and misrepresents the vendor's actual contribution. If your current setup recovers 50% of retryable failures and a new system recovers 65%, the meaningful number for pricing and business-case purposes is the 15-percentage-point gap, not the 65%.
How do you build an internal business case for payment recovery investment?
Start with your own MRR multiplied by your involuntary churn rate, typically 1 to 2 percentage points of total monthly churn, to calculate your annual revenue leak from payment failures. Run the same math on your own MRR and involuntary churn rate to get your actual figure. The strongest cases for finance stakeholders use historical transaction data showing actual failure rates by decline type and current recovery rates by failure category, then model what a specific incremental lift would be worth in recovered dollars. Performance-based pricing, where you pay only on revenue actually recovered, converts the investment from a budget line into a self-funding initiative with a calculable return from the first recovered invoice.
Related Articles
Retry Old Card or Wait for CAU? A Sep 2026 Guide
Card account updater retry logic sounds straightforward until you're staring at a mixed queue of expired cards, insufficient funds declines, and closed...
Defining Failed Payment Recovery for Subscription Businesses September 2026
Most subscription finance teams are solving the wrong problem. When a card declines and the account eventually closes, that loss lands in the churn column next...
Redefining Best Failed Payment Recovery Software Sep 2026
Vendor benchmarks for payment recovery software all tend to look the same: big recovery rate numbers, no control group, no way to know if your billing setup...
Stop losing revenue to failed payments
Join leading subscription businesses using Slicker to recover failed payments automatically.
Get Started